• Products
    • Corporate Salary Account
    • Convenient banking with enhanced benefits to suit the needs of our corporate salary customers

    • Fixed Deposit
    • Secure your money and watch it grow. Flexible tenures and attractive interest rates

    • Senior Citizen Scheme
    • Age is no excuse. Exciting benefits and higher interest rates to make your money work harder

    • Vehicle Loans
    • Easy and flexible finance options for vehicles, ranging from two wheelers, cars, commercial vehicles, earth movers to farm equipment

    • Affordable Home Loans
    • Your dream home is now in your budget. Super quick disbursals and attractive interest rates.

    • Loan Against Property
    • Expand your business, pay for further education or meet medical needs with a Loan against Property

    • Gold Loan
    • Put the power of gold to work. Instant financing with minimum documentation

    • Home Loan
    • Customisable home loan designed for our customers

    • Agri Loan
    • Enabling farmers to meet their credit needs, instantly Sow the seeds of a brighter future with a loan designed to help farmers

    • Personal Loan
    • Now nothing can hold back your aspirations. Instant Personal Loans with attractive EMIs

    • Medical Equipment Loan
    • Develop your healthcare facility and equip it with the latest technology in the industry

    • Credit Card
    • Discover endless benefits and privileges with our range of Credit Cards to suit your needs

    • Loan on Credit Card
    • Indus Easy Loan is a very convenient and quick option to get ready cash when you need it the most. Indus Easy EMI facility gives you the option to convert your high value credit card purchases into easy and flexible EMIs.

    • Duo Card
    • A single card that’s double the awesome! Get a credit and debit card in one

    • Debit Card
    • Make fast and secure payments on the go, wherever you are, with ease!

    • Commercial Cards
    • IndusInd Bank’s Corporate Card is designed to keep the organization’s cost objectives in mind. With this primary objective, our Corporate Cards can monitor & control employee expenses in addition to making re-conciliation hassle free.

    • Prepaid Card
    • Give your loved ones a gift that suits every occasion – the freedom of choice!

    • Forex Card
    • Carry convenience and security to wherever in the world choose to you go

    • My Family & Me
    • Protect what really matters. Avail of insurance for your whole family

    • My Business
    • Whatever your business, whatever its size – we have a solution that fits

    • Goal Calculator
    • Get smart and plan ahead. Calculate monthly instalments, investments and more

    • Mutual Funds
    • Investing gets easier when you have a systematic investment plan and a clear direction

    • Alternate Products
    • Diversify and customize your investments with the help of your fund manager

    • ASBA
    • Guiding you every step of the way as you unlock the potentials of your investments

    • Debit Card
    • Avail of the finest selections of debit cards to make payments on the go and online

    • Prepaid Card
    • One Card, Many Uses. Shop, Dine, Pay and Enjoy the Benefits of Convenience

    • Forex Card
    • Why count currency when you can count experiences with a Multi-currency Forex Card

    • FASTag
    • Cruise through toll plazas with FASTag, a cashless, convenient way of paying toll tax

    • Quick Pay
    • Reward, gift or surprise! Make instant transfers with QuickPay in minutes

    • Bharat QR
    • Scan. Pay. Go. Bharat QR is the newest, fastest way to pay!

    • Debit Card EMI
    • Power your purchase with a Debit Card EMI transaction without blocking your account balance and no processing fee. A safe and convenient way to do transactions with ease of repayments in EMI.

    • Forex Card
    • Why count currency when you can count experiences with a Multi-currency Forex Card

    • Inward Remittances
    • Initiate wire transfer from your local bank through their online / offline facility mentioning our correspondent bank details.

    • Fx Retail – Online
    • An online platform for anonymous, order-based dealing in USDINR (Cash/Tom/Spot).

    • What is PMJDY
    • Let nothing hold you back from forging your path to prosperity

    • Social Security
    • Designed with the best interest of you and your community at heart

    • Financial Literacy
    • Investing in your financial education so you can invest in your future

  • Make Payments
    • Credit Card Payment
    • Enjoy the ease of paying with your credit card…. And the exclusive privileges that come with it

    • Click Pay
    • Now pay your vehicle loan and affordable home loan EMIs with ease in just a few clicks.

    • Send Money Abroad
    • Now send money overseas to your family members, friends and other loved ones instantly from the convienence of your home.

    • SecurePay
    • Pay your insurance premium in a safe and secure manner instantly.

    • Bill Payment
    • Set up, automate, go! Never remember another bill due date again!

    • E-Mandate
    • Don’t worry about remembering due dates anymore. Set up an eMandate and let your EMIs be paid automatically

    • Payment NEFT / RTGS Facility
    • Make your Personal Loan/Business Loan account payment from any bank which offers NEFT / RTGS facility on their internet banking.

  • Digital Banking
    • Indusnet
    • Enjoy the freedom of managing your finances anywhere, anytime

    • IndusMobile
    • We shrank the bank to fit your phone. Access a suite of banking services on the go

    • IndusSmart
    • IndusSmart is an online Mutual Fund platform by IndusInd Bank to help its account holders learn, invest and plan for their investment goals.

    • Google Pay
    • Make smart, simple and secure digital payments via IndusInd Bank Cards on Google Pay

  • Apply Online
    • Personal Loan
    • Apply for a Personal Loan to meet your immediate cash needs

    • Vehicle Loans
    • Easy and flexible finance options for vehicles, ranging from two wheelers, cars, commercial vehicles, earth movers to farm equipment

    • Fixed Deposit
    • Open a fixed deposit online and maintain it online, too.

    • Mutual Funds
    • Save yourself the paperwork. Invest in mutual funds online

    • Insurance - IndiQwik
    • IndiQwik offers you easy insurance at preferential premium in just a few clicks!

    • Forex Card
    • A smart, efficient Forex Card so you enjoy your travels

    • Affordable Home Loans
    • Your dream home is now in your budget. Super quick disbursals and attractive interest rates.

    • FASTag
    • Cruise through toll plazas with FASTag, a cashless, convenient way of paying toll tax

    • Send Money Abroad
    • Now send money overseas to your family members, friends and other loved ones instantly from the convienence of your home.

    • Udyam Registration
    • Register for Udyam or update your Udyog Aadhaar and avail priority sector lending benefits by as offered by the Government of India.

  • Vehicle Auction
    • Indus EasyWheels
    • Pre-owned vehicle sales platform. Now bid for your favorite pre-owned cars and two-wheelers, anytime anywhere.

    • Register Now
    • Register on Indus EasyWheels completely FREE of cost with just your email ID and phone number

    • Login
    • Login to your Indus EasyWheels account

    • Blogs
    • Detailed analysis, industry news and interesting hacks to help expedite your journey to own your pre-owned vehicle

    • View all vehicles
    • We offer 360 degree vehicle information, inspection report and much more for you to make the right choice.

    • View all Two-Wheelers
    • View and select from our range of pre-owned two-wheeler vehicle options up for bidding

    • View all Cars
    • Choose from our range of pre-owned cars vehicle options up for bidding

    • FAQs
    • Have doubts? Here’s a set of frequently asked questions to help you get started.

  • Reach Us
    • Forms & Documents
    • Complete your formalities. Here’s everything you need in one place.

    • Charges & Fees
    • The most efficient personal banking services by IndusInd Bank

    • Contact Us
    • Need help? Simply connect to an IndusInd representative

    • Locate Us
    • Find out where your nearest IndusInd Bank is

    • FAQ's
    • Got questions? We have answers! Browse through our FAQs

    • Feedback
    • You make us better. Your opinion matters.

All posts by ANAND BHIDE

CIBIL Score Vs Credit Score – What’s the Difference?

Whether you want to access loans, apply for credit cards, or get low interest rates, a good credit profile is essential.  For credit profiles, two terms you would have come across are ‘CIBIL score’ and ‘credit score’.

While people use both the terms interchangeably, they have different meanings and implications. However, both play a vital role in determining your financial health. Hence, knowing the difference between a CIBIL score and a credit score is crucial. 

Understanding CIBIL Scores and Credit Scores

To understand credit scores vs CIBIL scores in a better way, we must first look at CIBIL in some detail. 

What is CIBIL?

The Credit Information Bureau (India) Limited, or CIBIL, is India’s first and most reliable credit information company. It collects and maintains credit records of individuals and businesses, including loans and credit card payments. Member banks and financial institutions provide these records.

What is a CIBIL Score?

The CIBIL Score is a three-digit number that ranges from 300 to 900. It represents an individual’s creditworthiness based on their credit history. It is taken from the credit report maintained by CIBIL and is the most widely recognised credit score in India. A higher CIBIL score implies better credit health. It increases the likelihood of loan approval and favourable terms.

What is a Credit Score?

A credit score is a general numerical representation of an individual’s creditworthiness. It is calculated based on the individual’s credit history and financial behaviour. 

A CIBIL score is a kind of credit score. However, there are other credit bureaus in India, such as Experian, Equifax, and CRIF High Mark, who provide their own credit scores. These scores may vary a bit because of different scoring models and algorithms used by each bureau.

Hence, the major difference between a CIBIL score and a credit scoreis that the former is CIBIL-specific, while the latter is general. Let’s explore some other differences as well. 

Difference Between CIBIL and Credit Scores

The following table explains the difference between a CIBIL score and a credit score: 

Parameter CIBIL ScoresCredit Scores
Scope and ProvidersProvided by the Credit Information Bureau (India) Limited (CIBIL).A general term referring to scores provided by various credit bureaus, including CIBIL, Experian, Equifax, and CRIF High Mark.
Scoring RangeRanges from 300 to 900.Ranges from 300 to 850, though it can vary depending on the credit bureau.
Usage and RecognitionWidely recognised and used in India, especially by lenders.All credit scores are used to gauge creditworthiness. However, lenders in India prefer the CIBIL score.
Calculation ModelBased on CIBIL’s specific algorithm and the credit report it maintains.Each credit bureau has its own algorithm and methodology.
Report ContentsDerived from the CIBIL report. It also includes detailed credit history, outstanding balances, payment behaviour, and more.Derived from the credit report of the respective bureau. It contains similar details but may have slight differences in data representation.

Also Read: People with a Low CIBIL Score Can Still Get a Credit Card- Here’s How

Conclusion

While both scores serve as indicators of creditworthiness, knowing the nuances of a credit score vs a CIBIL score can help you navigate the borrowing landscape with ease.

Ready to improve your credit profile? Consider applying for a Credit Card with IndusInd Bank. We offer a diverse range of Credit Cards like the Platinum RuPay Credit Card for seamless UPI transactions, the Nexxt Credit Card with interactive elements, the EazyDiner Credit Card for culinary aficionados, the Avios Visa Infinite Credit Card for frequent travellers, and more. 

Browse through our website to explore various Credit Cards and find the one that best suits your needs. Apply now for Credit Card and enhance your financial journey with IndusInd Bank!
Share This:

Is 700 a Good Credit Score, or Bad?

Your credit score is an important aspect of your financial health. It influences your ability to get loans, credit cards, and favourable interest rates. A 700-credit score is a common benchmark people wonder about: Is it good enough to secure positive loan terms? Does it reflect a healthy financial profile?

Let’s understand where this score stands in the broader range of credit scores so that you make better financial decisions.

Is a 700 Credit Score Good?

  • A 700-credit score is considered good. Credit scores range from 300 to 900 in India. The higher the score in this range, the better the individual’s creditworthiness.
  • A 700-credit score falls within the ‘Good’ umbrella, suggesting that you are a reliable borrower. 
  • While it is not at the top end of the scale, a 700-credit score implies you have a solid credit history with responsible financial behaviour. 
  • This score can qualify you for most credit cards and loans. However, you might not always get the best interest rates available.

What Happens If You Apply for a Credit Card with a 700 Credit Score?

Most banks would approve credit cards for a 700-credit score. However, you must consider certain aspects:

1. Interest Rates

While you can get approved for many credit cards for a 700 score, the interest rates you receive may not be the lowest available. Cards for those with ‘Very Good’ or ‘Excellent’ credit might offer better rates.

2. Credit Limits

You might receive moderate to high credit limits depending on your income and overall credit profile. A 700-credit score shows you manage credit well, which can be appealing to lenders.

3. Approval Chances

A 700-credit score increases your chances of approval. However, there is no guarantee of the best credit cards for a 700-credit score. You might encounter some limitations, such as fewer rewards compared to applicants with higher scores. 

However, the credit card issuers consider various factors beyond your credit score. This can include your income, debt-to-income ratio, and credit history. 

Tips on Improving Your Credit Score and Maintaining It

While a 700-credit score is good, aiming for a higher score can provide more financial benefits. Here are some ways to improve and maintain your credit score:

1. Pay Your Bills on Time

Make it a point to pay your bills on time each month/billing cycle. Payment history impacts your credit score on a major scale.

2. Keep Credit Utilisation Low

Credit utilisation refers to how much credit you are using compared to the total credit limit available to you. High credit utilisation can lower your score. Try to use less than 30% of your credit limit.

3. Avoid Opening Too Many New Accounts

Every time you apply for new credit, you lower your score. Hence, apply only when necessary.

4. Maintain Long-Term Accounts

Your credit history’s duration also affects your score. It is crucial to keep old credit accounts open and in good standing.

Also Read: What Happens When You Default on Credit Cards?

Conclusion

A 700-credit score is a solid indicator of good creditworthiness. While you can get a credit card for a 700 score, there is still room for improvement. Keep the above steps in mind to enjoy greater financial flexibility and access to better credit offers.

Looking for a credit card that complements your 700-credit score? Explore IndusInd Bank’s range of Credit Card offerings today! 

IndusInd Bank has a diverse range of Credit Cards to suit the financial needs and credit score profiles of different individuals. Whether you are looking for high rewards programs, cashback offers on top brands, travel privileges like airport lounge access, or simply the convenience of a credit card, we have a solution for you. 

Apply now for a Credit Card with IndusInd Bank now to get started! 

Disclaimer:

The information provided in this article is generic and for informational purposes only. It is not a substitute for specific advice in your circumstances. Hence, you are advised to consult your financial advisor before making any financial decision. IndusInd Bank Limited (IBL) does not influence the views

 of the author in any way. IBL and the author shall not be responsible for any direct/indirect loss or liability incurred by the reader for making any financial decisions based on the contents and information.

Share This:

What Should You Do if Your Credit Card Application Gets Rejected?

Imagine you’ve carefully filled out a credit card application, submitted all necessary documents, and eagerly await your approval. But then, the unthinkable happens—your credit card application gets rejected. It is a frustrating experience, leaving you questioning where you went wrong. Many face this scenario, and it is essential to understand why this happens and how to navigate it. This blog will guide you through what your next steps should be after this. This can help you improve your chances next time so you wouldn’t have to wonder, “why did my credit card application got declined”.

Understand the Reasons Behind Rejection

When your credit card application gets denied, it’s crucial to identify the reasons. Here are some common causes:

  • Poor Credit History: Lenders check your credit history to gauge your creditworthiness. A low credit score can be a red flag.
  • Insufficient Income: Credit card issuers require a specified minimum income level. This ensures you can repay the credit. Falling short of this requirement can lead to rejection.
  • Existing Debt: Existing debt, which is high relative to your income, can cause troubles. It can make lenders hesitant to extend more credit.
  • Faulty Application: Maybe your credit card application got declined because of missing or incorrect information in your application.  

Review Your Credit Report

After facing a rejection, review your credit report for errors or issues. You can get a free credit report from credit bureaus. Look for inaccuracies or old information that can negatively impact your score. If you find errors, report them immediately to get them corrected. Monitoring your credit report helps you stay on top of your financial health.

Improve Your Credit Score

If poor credit history is the reason for rejection, take steps to improve your credit score:

  • Timely Payments: Pay your bills on time to build a positive payment history.
  • Reduce Debt: Lower your existing debt levels to improve your credit utilisation ratio.
  • Limit Credit Inquiries: Do not apply for multiple credit cards or loans in a short period.

Consider a Secured Credit Card

A secured credit card is an excellent option if your application was declined because of a poor credit history. A secured credit card requires a fixed deposit as collateral. This makes it less risky for the lender. Using a secured card responsibly can help rebuild your credit score. It also can make you eligible for an unsecured credit card in the future.

Ensure Accurate and Complete Applications

Double-check your application before submitting it. Ensure all information is accurate and complete. Missing details or incorrect information leads to an automatic rejection. Provide all necessary documents and ensure they are up to date.

Evaluate Your Income and Expenses

If your application was declined because of insufficient income, evaluate your financial situation. Look for ways to increase your income or reduce expenses. Demonstrating a stable and sufficient income can improve your chances of approval.

Reapply Strategically

After addressing the issues that led to your rejection, consider reapplying. But don’t rush into it. Focus on improving your credit score and financial situation. When reapplying, choose a card that aligns with your credit profile and needs.

Explore Alternative Options

If your requests for credit cards are declined by VISA and MasterCard, explore alternatives like RuPay credit cards. RuPay cards offer similar benefits and are widely accepted across India. IndusInd Bank provides a RuPay credit card called the IndusInd Bank Platinum RuPay Credit card. This card can be a stepping stone to building your credit history.

Also Read: People with a Low CIBIL Score Can Still Get a Credit Card: Here’s How

Conclusion

Facing a rejected credit card application can be disheartening, but it isn’t the end of the road. If you understand the reasons behind the rejection, take corrective measures. This can improve your chances of approval in the future. Monitor your credit report, maintain a healthy credit score, and take other steps to improve your chances. Don’t let a rejection deter you—take control of your financial future today!

Looking for a credit card tailored to your needs? Consider exploring IndusInd Bank’s credit cards. From secured credit cards to RuPay cards, IndusInd Bank has a variety of options designed to meet your financial requirements.

Apply now and learn more about IndusInd Bank Credit Cards and find the perfect card for you.

Share This:

What is OTP in Credit Card Transactions?

An OTP or a one-time password has become an integral part of online transactions and banking in recent times. Especially for credit card transactions, OTP ensures an added layer of security and prevents misuse. This has become especially important as the number of digital payment fraud cases reported by banks increased by 70.64% to ₹2,604 crore in the six-month period from October 2023 to March 2024. This article discusses what OTP means in the context of credit cards, how it works, its benefits, and some tips for using OTP securely.

How OTP Works in Credit Card Transactions

To understand how OTP works, let us first learn what is OTP in a credit card transaction.

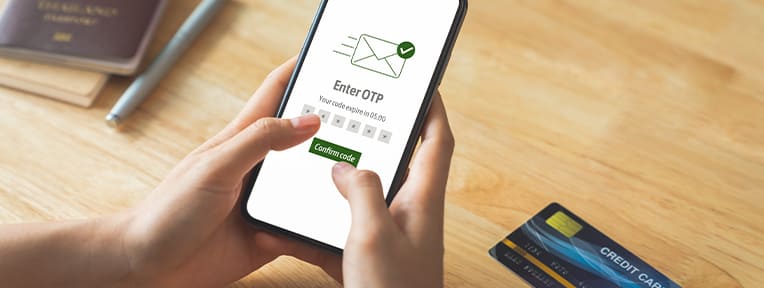
When you make an online purchase through a credit card, you need to fill in the card details like card number, expiry date, CVV number, etc. Once you submit this information, the bank initiates a request for OTP to verify it’s really you who is making the purchase. 

An OTP in credit card transactions is a random four or six-digit numerical code sent to your registered mobile number or email ID. You need to enter this OTP while completing the transaction to confirm your identity.

The OTP is auto-generated and keeps changing, so it cannot be predicted or reused. Once you submit the valid OTP, the transaction is approved by the bank. If an incorrect OTP is entered multiple times, the bank may block the card to prevent misuse.

Importance of OTP in Credit Card Transactions

  • Adds a layer of security over static passwords
  • Ensures the cardholder alone can access the card and make purchases
  • Prevents identity theft and misuse if card details are compromised
  • Allows the bank to authenticate the real cardholder before approving transactions
  • Simpler than remembering complex passwords for each transaction
  • Can alert users if unauthorised transactions are attempted

Benefits of Using OTP in Credit Cards

Some key benefits of using OTP in credit card transactions include:

  • Enhanced security for card and accounts
  • A one-time password solution for users
  • Instant alerts to cardholders for each transaction
  • Faster processing of transactions after OTP verification
  • Reduces fraud and identity theft risks
  • Valid only for specific session, cannot be reused
  • Simple and hassle free for customers
  • Provides real-time confirmation of payments
  • Wide applicability for varied transactions

Using OTP Securely for Credit Cards

Security tipDescription
ConfidentialityNever share your OTP with anyone, including family, friends, or bank officials. You should be the only one who knows it
Website securityBefore entering your card details, ensure you’re on a secure website. Look for “HTTPS” in the address bar instead of just “HTTP”
OTP sender verificationVerify that the OTP is sent from your bank’s registered phone number or email ID you have on file
Phishing awarenessDon’t click on unknown links or respond to suspicious requests for your OTP. Phishing scams try to trick you into revealing it
Device securityKeep an updated antivirus program running on the device you use for online transactions
Network securityUse secure Wi-Fi or mobile data for transactions. Avoid using public Wi-Fi networks
Transaction controlIf you won’t be using your card for a long time, consider setting transaction limits with your bank
Account monitoringRegularly monitor your credit card activity to identify any unauthorised OTP requests or suspicious transactions
Bank supportIf you experience any issues with OTPs or suspect fraudulent activity, contact your bank immediately for assistance

Also Read: What is Skimming of Credit Cards?

The Importance of Security

Keeping your credit card and related information secure is extremely important to avoid misuse and fraud. IndusInd Bank provides various facilities to ensure enhanced security for credit card transactions, like OTP-based purchases, updated EMV chip cards, secure online portals, etc. IndusIndBankCredit Cards with one-time passwordsalso come equipped with features like account monitoring, fraud detection, transaction alerts, and the ability to block the card instantly.

Apply for credit card seamlessly through the official IndusInd Bank website to get a credit card that follows stringent security protocols. IndusInd Bank offers a range of credit cards like the Legend Credit Card, Platinum RuPay Credit Card, EazyDiner Platinum Credit Card, etc., that provide a host of rewards and benefits while maintaining bank-level security. The competitive interest rates and instant online approval process further make IndusInd Bank Credit Cards a preferred choice for safe cashless transactions.

Conclusion

OTPs provide credit card users with a time sensitive, one-use password to authenticate transactions, preventing misuse while maintaining convenience. By understanding how it works and using OTPs securely, credit card holders can reap its benefits while enjoying peace of mind against online frauds.

Apply now for an IndusInd Bank Credit Card!

Share This:

How to Pay a Credit Card Bill Using another Credit Card?

Paying one credit card bill with another credit card is usually not available as a standard direct payment option. However, you can use indirect methods such as a balance transfer, cash advance, or supported e-wallet.

These options can help during a temporary cash-flow problem, but they do not remove the debt. They can also involve processing fees, interest charges, and additional credit exposure. Understand the cost and repayment terms before choosing one.

Ways to Pay Credit Card Bill with another Credit Card

Balance Transfer

A balance transfer allows you to move an outstanding balance from one credit card to another eligible card. The new card issuer either pays the old card issuer directly or provides an approved process for transferring the balance.

A balance transfer can be useful when the new card offers a lower interest rate or a fixed repayment plan. Before applying:

  1. Check the exact amount outstanding on the existing card.
  2. Compare the balance transfer interest rate with the current rate.
  3. Check the processing fee, GST, repayment tenure, and post-offer interest rate.
  4. Confirm that the available credit limit is sufficient.
  5. Continue paying the existing card until the transfer is completed and confirmed.
  6. Repay the transferred balance on the new card as per the agreed schedule.

A balance transfer is beneficial only when the total cost is lower and you have a clear plan to repay the new balance.

Cash Advance

A cash advance involves withdrawing money from one credit card and using it to pay the bill of another card.

This method is generally expensive because it attracts a cash advance fee. Interest on cash advances also starts from the date of withdrawal instead of receiving the usual interest-free period.

Use this option only in a genuine emergency. Check the cash advance limit, withdrawal fee, interest rate, and repayment terms before proceeding.

E-Wallet or Payment Platform

Some e-wallets and payment platforms allow users to load money using a credit card and use the balance for bill payments. However, this facility is not available on every platform or for every card.

Before using this route, check:

  • Whether credit-card loading is permitted
  • Whether credit-card bill payment is supported
  • The convenience fee and applicable taxes
  • Daily or monthly transaction limits
  • Whether the transaction qualifies for rewards or cashback
  • Whether additional verification is required

Use only the official application or website of the payment platform. Never share your card PIN, OTP, CVV, or net-banking password with anyone.

Pros and Cons of Paying a Credit Card Bill Using another Credit Card

Using another credit card to pay an existing bill has both advantages and disadvantages.

Possible advantages include:

  • It can help you avoid a late payment when you are facing a temporary shortage of funds.
  • A balance transfer can reduce the interest cost if the new rate and fees are lower.
  • It can combine multiple outstanding balances into one repayment schedule.
  • It can give you additional time to organise your finances.

The disadvantages to consider:

  • Processing fees, cash advance fees, convenience fees, and GST can increase the total cost.
  • Cash advances attract interest from the transaction date.
  • The debt is transferred or extended; it is not cancelled.
  • Using a large part of the new credit limit can increase your credit utilisation ratio.
  • A promotional balance transfer rate can end, after which the regular interest rate applies.
  • Rewards or cashback are not guaranteed on balance transfers, cash advances, or wallet-loading transactions.
  • Missing the new card’s payment due date can create another late payment and further increase the debt.

Use this option only when it solves a short-term problem and you can repay the new outstanding amount on time.

What are better ways to stay on top of your credit card bills?

The safest way to manage a credit card bill is to pay the Total Amount Due from your bank account before the due date. This helps you avoid interest on eligible transactions and prevents the outstanding balance from building up.

If you use an IndusInd Bank credit card, you can pay through authorised channels such as IndusNet, the IndusInd Bank Mobile Banking app, NEFT, Credit Card Quick Pay, NACH, auto-debit, and other payment methods listed by the bank.

You can also follow these habits:

  • Set a reminder a few days before the payment due date.
  • Activate auto-debit only after ensuring that your bank account has sufficient funds.
  • Pay more than the Minimum Amount Due whenever possible.
  • Stop fresh spending on the card if the existing balance is becoming difficult to repay.
  • List all card balances, interest rates, fees, and due dates in one place.
  • Prioritise repayment of the card charging the highest interest.
  • Contact the card issuer early if you cannot pay the full amount.
  • Consider a structured repayment or balance transfer only after comparing the complete cost.

Paying only the Minimum Amount Due can prevent the account from being treated as overdue, but interest continues on the unpaid balance.

Stay Ahead of Your Credit Card Bills Without Adding More Debt

Using one credit card to pay another should be a carefully considered decision, not a regular repayment habit.

A balance transfer can make sense when it offers a lower overall cost and you can clear the transferred amount within the agreed period. Cash advances and wallet-based payments require greater caution because their fees and interest can quickly increase your financial burden.

Whenever possible, pay your credit card bill directly through your bank account and use authorised payment channels. If you need more practical guidance, read Smart Spending: The Advantages of Using Credit Cards for Payments.

Frequently Asked Questions

Q1. Are reward points or cashback earned when paying a credit card bill through an e-wallet using another credit card?

Rewards and cashback are not guaranteed. Many card issuers exclude wallet loading, balance transfers, cash advances, and bill payments from reward programmes. Check the terms of both the credit card and e-wallet before completing the transaction.

Q2. Can a balance transfer help reduce the interest paid on existing credit card debt?

Yes. A balance transfer can reduce the interest cost when the new interest rate and all applicable fees are lower than the cost of keeping the balance on the existing card. Compare the processing fee, GST, repayment tenure, and post-offer rate before deciding.

Q3. What factors should be compared before choosing a balance transfer credit card?

Compare the balance transfer interest rate, processing fee, GST, maximum transferable amount, available credit limit, repayment tenure, promotional-period terms, post-offer interest rate, late-payment charges, and foreclosure or pre-closure conditions.

Q4. Does using one credit card to pay another affect the available credit on both cards?

Yes. The card used for the payment loses available credit by the amount charged or transferred. The balance on the receiving card also occupies its credit limit. The available limit on the original card increases only after the payment is credited and processed.

Share This: